The Federal Statute That Made Sand Hill Road Possible
Before Congress created the Small Business Investment Company in 1958, the institutional infrastructure for early-stage investing simply did not exist.
01 / MoneyOne Statute, One New Asset Class
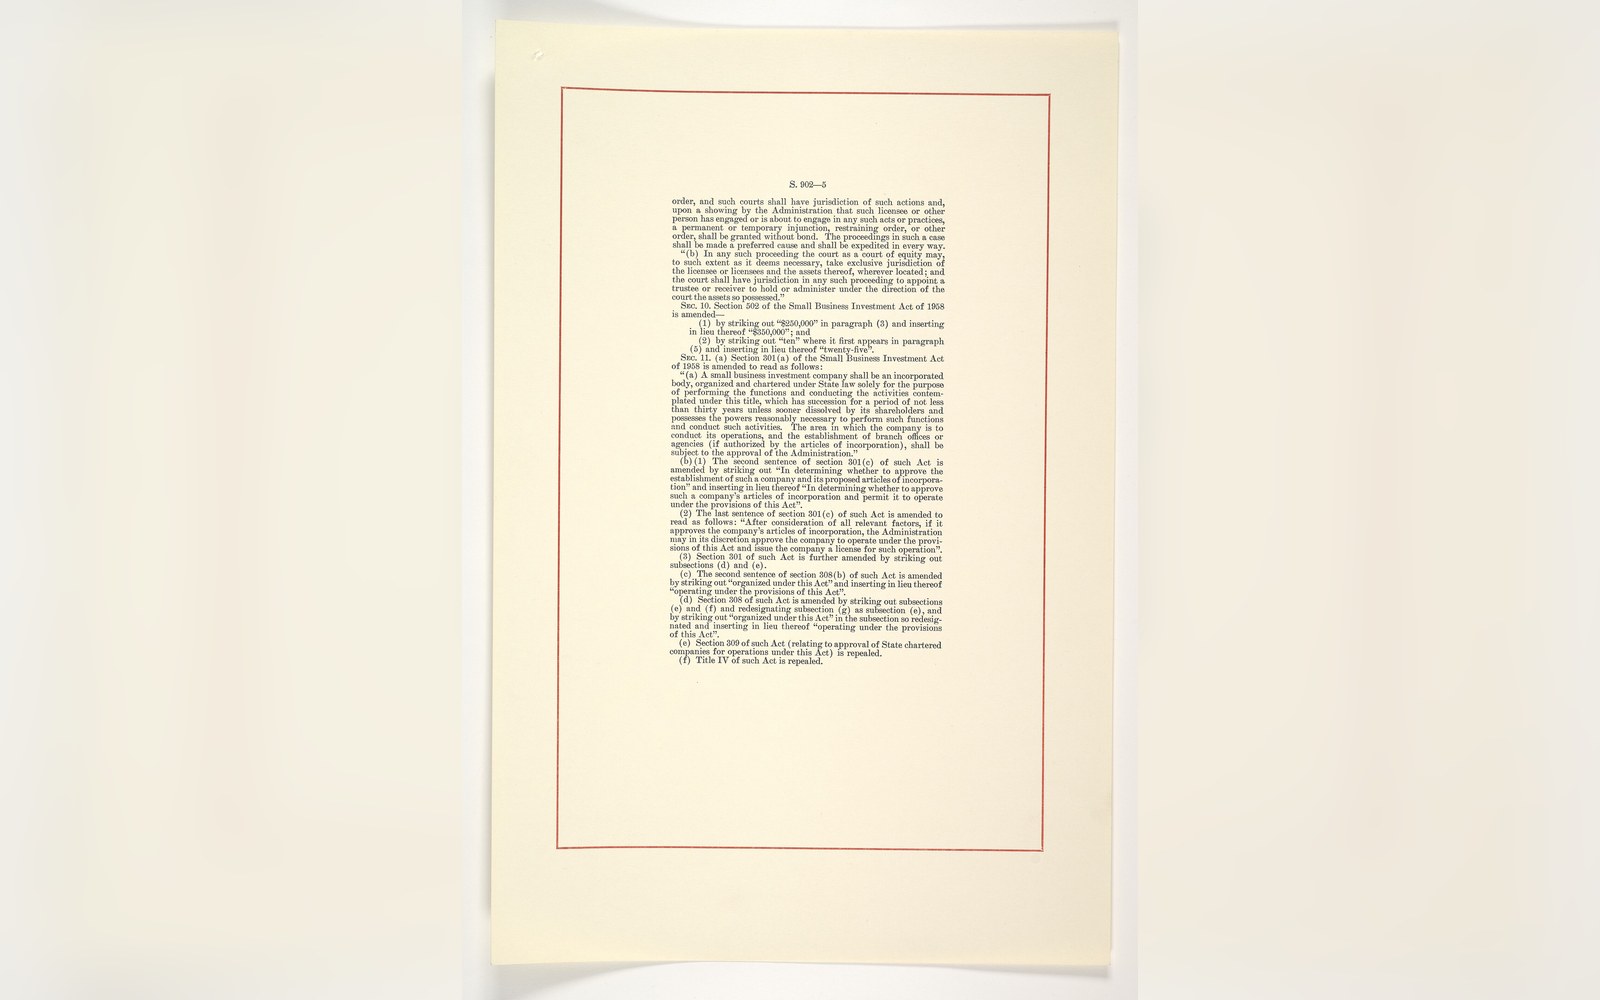
The Small Business Investment Act, signed by President Eisenhower on 21 August 1958, authorized the creation of Small Business Investment Companies — SBICs — as federally licensed private funds that could borrow money from the Small Business Administration at subsidized rates and deploy it into early-stage companies. For every dollar a private investor put in, the federal government would supply two or three more. The leverage was the point: it made venture-scale bets viable for institutions that could not otherwise justify the risk profile.
The timing was not accidental. Fairchild Semiconductor had been founded the previous year, and Arthur Rock's role in assembling its capital had already demonstrated both the appetite and the institutional gap. The SBIC program gave that gap a legislative answer. Within two years of the Act's passage, hundreds of SBICs had been licensed, and a portion of the capital flowing through them was reaching exactly the kind of technology-oriented startups the program's authors had imagined.
The program's record was uneven. Many early SBICs were run by banks and insurers more comfortable with debt than equity, and a significant share of licensed funds eventually failed or were wound down. But the structure itself — a licensed, regulated vehicle using leverage to fund high-risk, high-growth businesses — established the legal and conceptual framework that private venture capital would later inhabit without the federal subsidy. Arthur Rock and others who had operated around the SBIC world moved toward purely private limited partnerships through the 1960s, and by 1972, when Kleiner Perkins and Sequoia Capital both opened on Sand Hill Road, the dominant form was the private LP rather than the government-backed SBIC.
The Act did not create Silicon Valley. But it created the first federally recognized category of institution whose explicit purpose was equity investment in small, unproven businesses — a statutory legitimation that mattered when pension funds, insurers and banks were deciding whether such activity fell within their mandates. The 1979 ERISA clarification that opened pension money to venture funds built on ground the 1958 Act had prepared. One statute rarely does all the work; this one did the first part.